News
“Newcomer” Paradox: Years in business yet still struggling to access credit after corporate transformation
 03/03/2026
In the context of a gradually recovering economy, the trend of transforming from household businesses into micro-SMEs is on the rise, aiming to meet requirements for scaling up, increasing operational transparency, and accessing formal financial resources. However, in fact, many long-standing business owners still face difficulties accessing bank credit because their newly registered enterprises are considered too “young” in legal terms.
According to the General Statistics Office, Vietnam currently has over 5 million household businesses, contributing around 30% of GDP and providing employment for tens of millions of workers. Each year, tens of thousands of these businesses are converting to a corporate model, yet the majority become micro-enterprises with limited capital, incomplete accounting systems, and constrained collateral – all factors that make accessing bank credit a challenging task.
Removing the “Seniority” barrier for new enterprises
One of the most common obstacles for newly established micro-SMEs is the requirement regarding operational tenure. In practice, many banks still require a business to have been active for 6–12 months to qualify for credit, even if the business owner has a stable track record from previous operations.
To address this paradox, SeABank has updated its business loan package, specifically designed for micro-enterprises and household businesses undergoing transformation. Under this scheme, businesses from 3 months of operation can be considered for credit, with loan limits and terms flexibly tailored to actual needs.
Specifically, for working capital needs, loan terms can extend up to 36 months, enabling businesses to proactively manage inventory, rotate capital, and stabilize cash flow. For loans aimed at investing in machinery, equipment, or expanding production facilities, terms can last up to 120 months. For loans to purchase or acquire real estate for business purposes, terms can extend up to 300 months, alleviating repayment pressure during the initial stages.
Supporting the Micro-enterprise ecosystem
A survey by the Vietnam Association of Small and Medium Enterprises shows that nearly 60% of businesses face difficulties accessing bank credit, particularly in the early stages of business model transition, mainly due to insufficient collateral, weak credit history, and complex loan documentation. To address these constraints, SeABank has customized a credit assessment process for this customer segment, ensuring simple and fast procedures that are closely aligned with the actual operations of SMEs.
Repayment methods are flexible with options to pay interest monthly or quarterly; principal repayment can be scheduled monthly, quarterly, semi-annually, or at the end of the term, depending on the business cycle of each industry.
In addition to procedural issues, collateral remains a major bottleneck for new businesses. SeABank has expanded the range of acceptable collateral under the SeAPro loan package. In addition to real estate, savings deposits, and valuable papers, the Bank also accepts vehicles such as passenger cars with up to 16 seats, trucks, and pickup trucks, which are commonly used in micro-SME operations.
This approach enables many businesses to make the most of their existing resources to access timely funding, rather than having to delay production or business plans due to a lack of traditional collateral.
According to SeABank representatives, designing “tailored” credit products for newly established businesses are designed not only to expand credit access but also to build a sustainable SME ecosystem, supporting the private sector – a key driver of economic growth.
In the context of the Government’s goal to strongly develop the SME sector, flexible financial solutions that are closely aligned with practical needs are expected to help remove capital bottlenecks, enabling business owners to confidently transform their business models and enhance competitiveness.
Related News
SeABank was honored by VISA for applying advanced data to improve card portfolio management efficiency 12/11/2026
SeABank records VND1,315 billion profit in Q3/2026, up 37.5% YoY, total assets exceed VND429,376 billion 04/11/2026
SeABank completes charter capital increase to VND34,688 billion 02/11/2026
SeABank ranked 16th in the Top 50 Vietnam Best Profitable 29/10/2026
SeABank publishes Sustainable Finance Framework 26/10/2026
SeABank was honored by VISA for applying advanced data to improve card portfolio management efficiency
Southeast Asia Commercial Joint Stock Bank (SeABank, HOSE: SSB) was recently awarded "Leadership in Data-driven Portfolio Optimization 2026" by the international card organization VISA at the VISA Annual Client Conference 2026 held in Hue. The award recognizes the effectiveness of SeABank's deployment of data analytics solutions in card portfolio management, promoting payment growth and service development towards personalization.
12/11/2026
Read more

SeABank records VND1,315 billion profit in Q3/2026, up 37.5% YoY, total assets exceed VND429,376 billion
Profit-before-tax (PBT) of Southeast Asia Commercial Joint Stock Bank (SeABank, HOSE: SSB) reached nearly VND1,315 billion in Q3/2026, up 37.5% YoY. For the first 9 months, the Bank recorded VND 3,940 billion in PBT. Total assets reached VND429,376 billion, up 8.31% from the beginning of the year. Outstanding credit grew 11.3%, and the non-performing loan (NPL) ratio was controlled at 2.28%.
04/11/2026
Read more
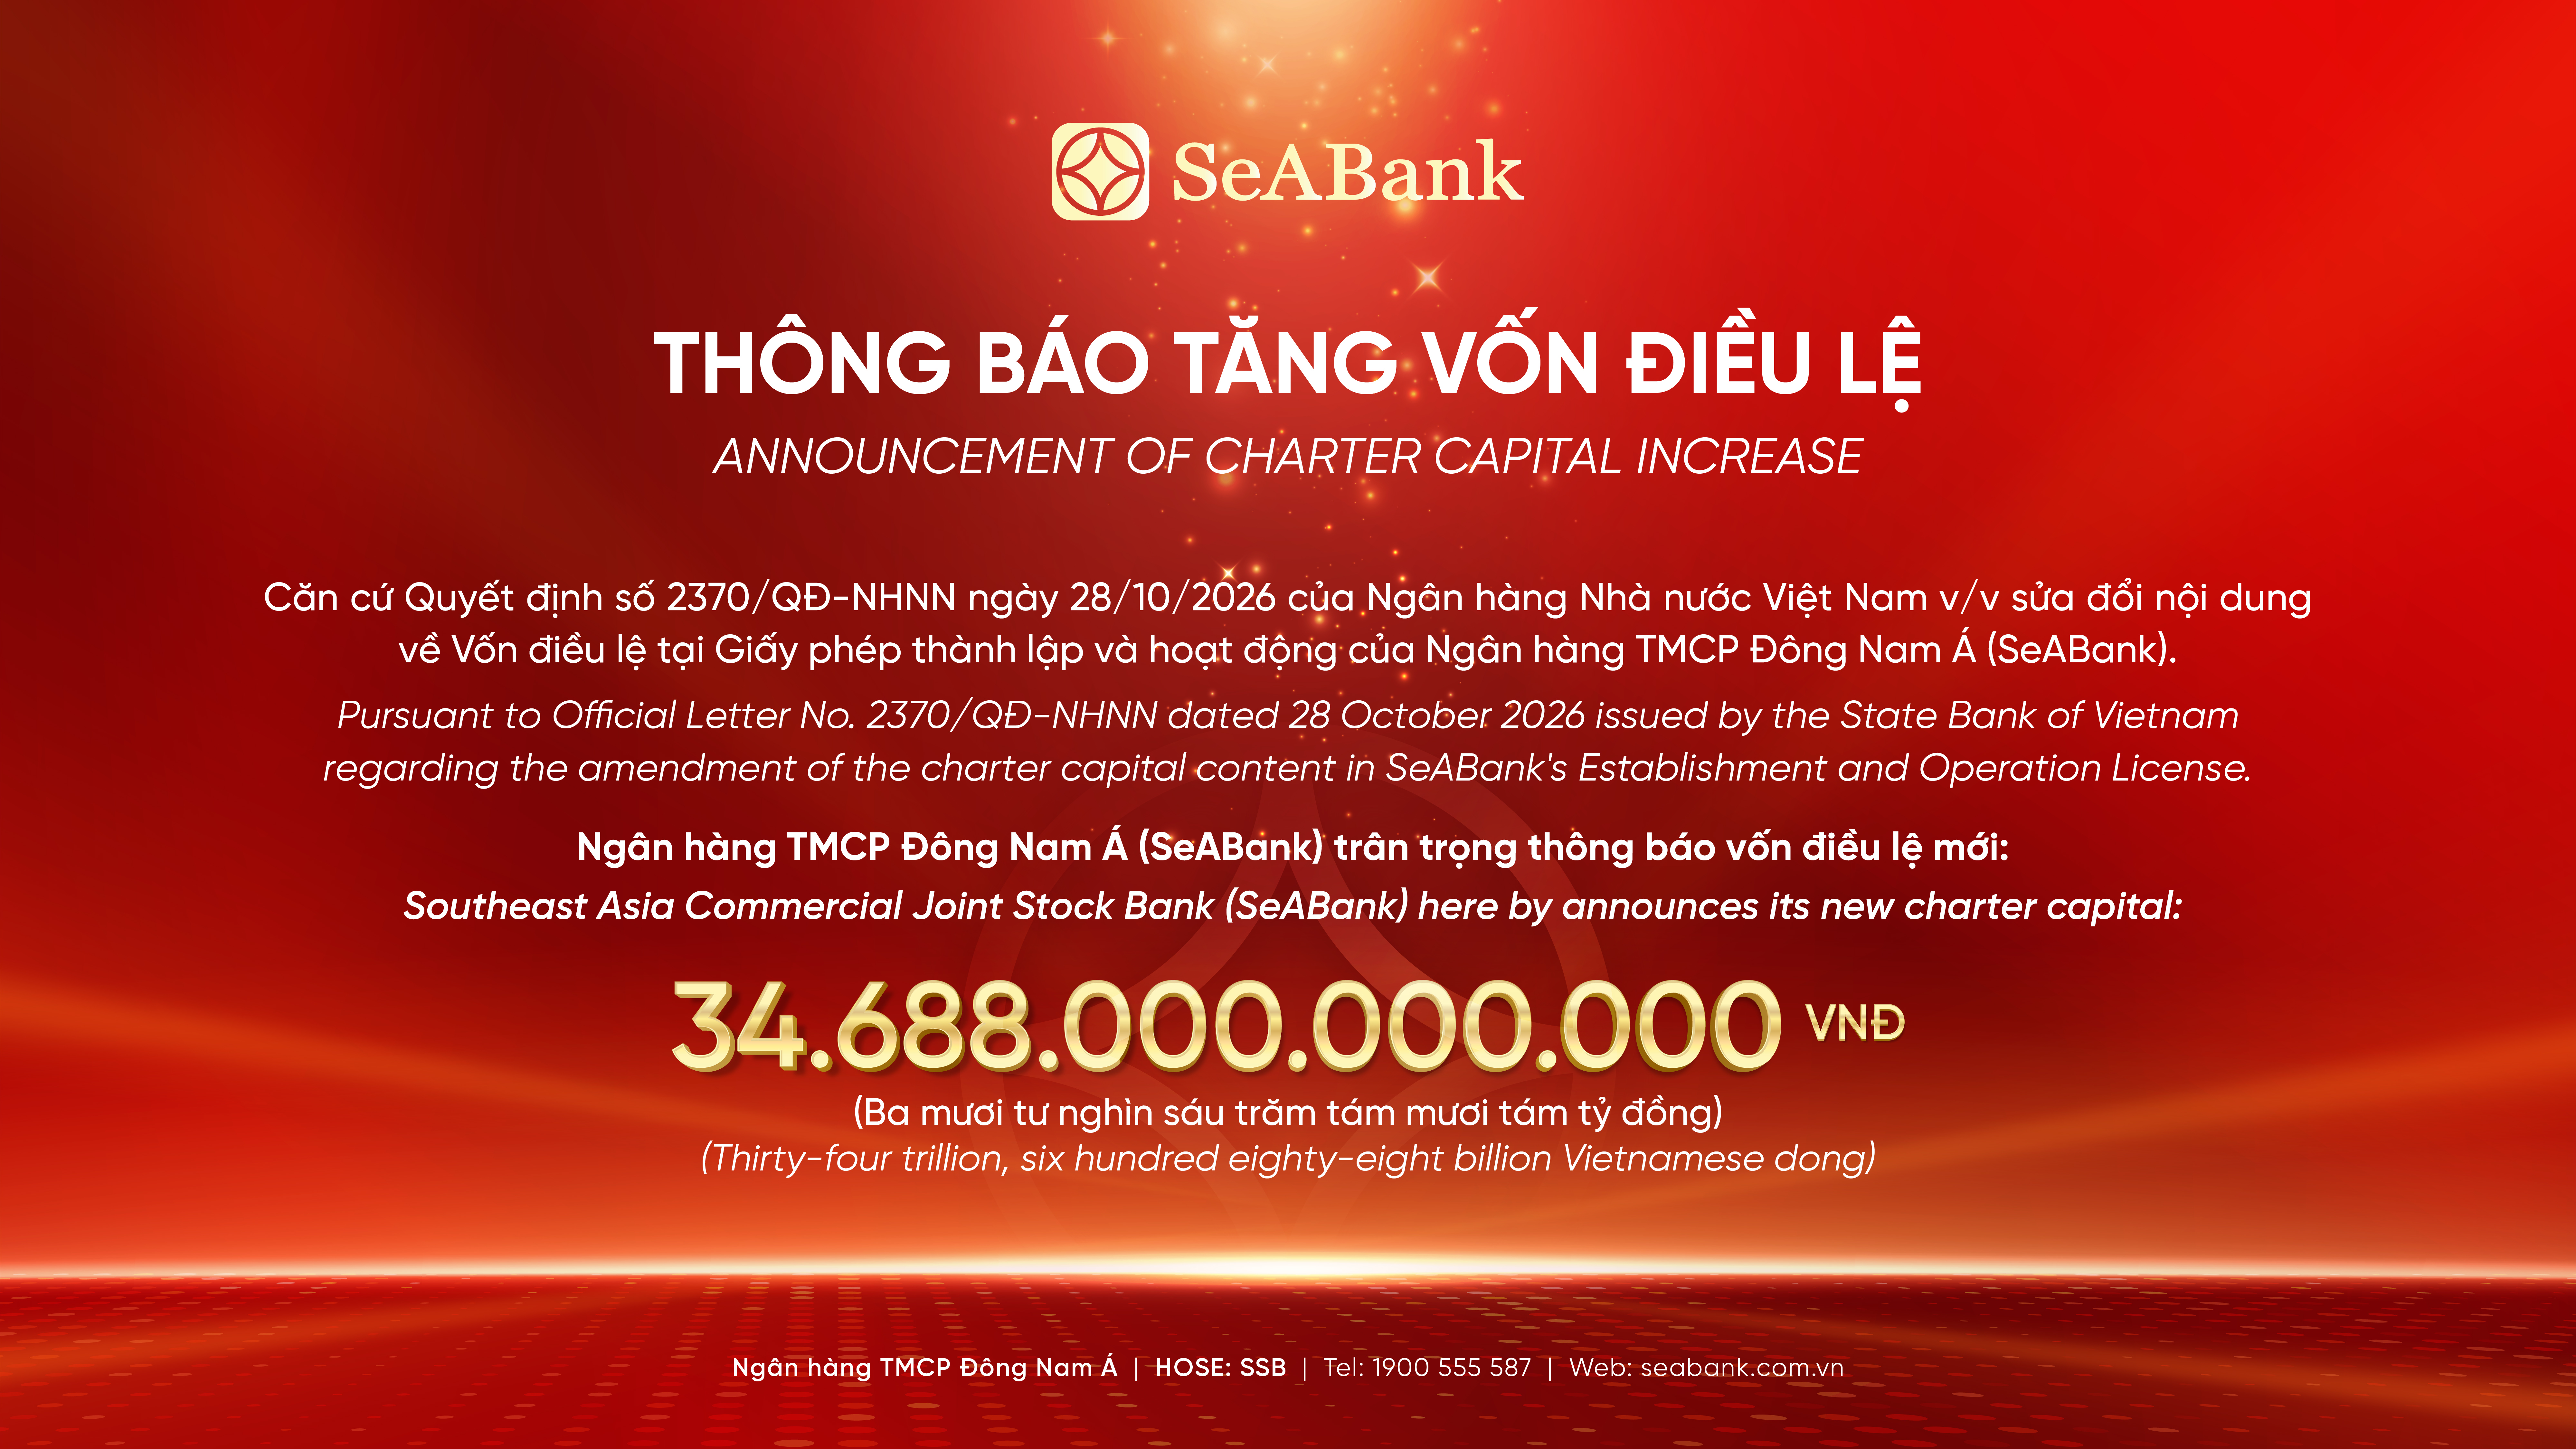
SeABank completes charter capital increase to VND34,688 billion
Southeast Asia Commercial Joint Stock Bank (SeABank, stock code: SSB) has officially received approval to increase its charter capital to VND34,688 billion (approx. US$1.33 billion). The additional capital will strengthen the Bank’s financial capacity and improve its capital adequacy ratios, while reflecting a balanced approach to developing both financial resources and high-quality human capital, laying the foundation for sustainable growth.
02/11/2026
Read more